From a dinar that could buy the world… to a dollar that buys Iraq
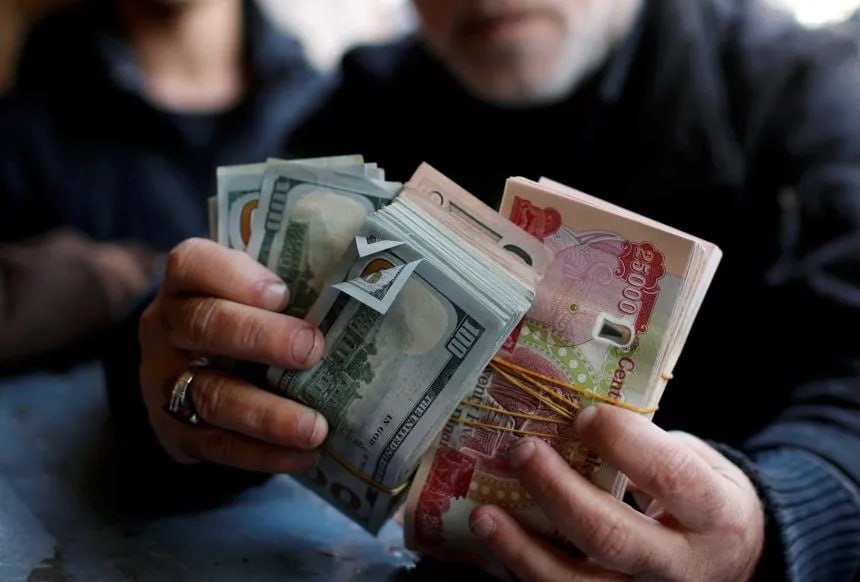 Today, the Iraqi stands before the history of his dinar as one stands before an old photograph of a house he once lived in; he contemplates its features, searches for something familiar, then returns to the present and finds that the place is the same place, but things have lost much of their meaning. IraqEconomic Reports
In 1975, one US dollar was worth approximately 0.295 Iraqi dinars, meaning one dinar was worth more than three dollars at the nominal exchange rate at the time. Today, one dollar requires approximately 1310 dinars at the official rate.
But the gap between the two figures is not just a collapse in the value of a banknote. It is a gap that encapsulates decades of wars, blockades, sanctions, unrest, and oil shocks, and at the same time reveals an economy whose structure has changed, but which has not succeeded in freeing itself from its chronic dependence on a single resource.
But behind this monetary collapse lies a bigger question: How did the Iraqi economy change so much that its currency lost so much of its value? Or rather: What happened to the economy that was behind it?
Currency is more than just a piece of paper with a number on it; it is a reflection of the economy’s ability to produce, of people’s trust in its institutions, and of its ability to transform its resources into sustainable value.
The dinar does not weaken in a vacuum.
When domestic production declines, the need for imports increases, and public spending becomes hostage to oil revenues, the currency becomes more vulnerable to pressure, no matter how full the state coffers may seem of dollars.
Herein lies the great Iraqi paradox: a country rich in resources, but which has not fully transformed its wealth into a capabilities-rich economy.
Oil remains the backbone of the country’s revenues and exports. World Bank data indicates that in 2025 it accounted for approximately 88% of government revenues and 91% of merchandise exports.
This means that a rise in the price of a barrel of oil not only increases state revenues but also expands its spending capacity, stimulates demand, and increases the need for imports in an economy whose non-oil production base remains limited. When oil prices fall, this cycle contracts, and its effects are felt in the budget, investment, employment, and income.
Here, oil moves from the screens of global markets into the lives of citizens. It impacts salaries, food prices, transportation costs, rent, education, and medicine.
Therefore, the citizen does not ask about the gross domestic product or the size of the reserves as much as he asks a harsher question: Where does my country’s wealth go if I do not feel it in my life?
The answer begins with the difference between rent and capital.
Oil can finance spending, but that spending ends when its effects wear off. However, if a portion of oil revenue is channeled into investments that boost productivity in industry, agriculture, transportation, energy, and finance, it creates productive capacity that endures long after the initial dollar is spent.
Here the function of oil must change: oil should not be the economy, but rather a means to build an economy that is less dependent on it. EconomicStability Analysis
The true strength of the dinar does not begin with the central bank’s screen, but with the factory, the field, the port, the small company, the bank that finances a productive project, and the university that produces skills needed by the market.
A state can defend an exchange rate, but it cannot defend it forever in the face of an economy that does not produce enough.
It can provide dollars, but it cannot make importing a permanent substitute for production.
It can spend billions, but billions only become development when they are converted into productivity, jobs, real income, and exports.
Therefore, comparing the 1975 dinar with today’s dinar is not a naive call to restore an old exchange rate. It reflects a larger question:
Why hasn’t the enormous oil wealth been transformed into a productive base that makes the economy less fragile, and the citizen less afraid of the movement of the dollar?
That is the real test.
It’s not about how much the dinar is worth against the dollar, but rather how much value the Iraqi economy can generate behind each dinar.
A rich country is not just one that owns oil, but one that knows how to use it to build an economy that can, one day, live without it.
A strong currency is not one that has an impressive number, but one that is based on a strong economy, stable institutions, real production, and confidence that does not need to look at the dollar screen every morning to feel reassured.
In the end, the value of the paper may break, but the story will only break when Iraq fails to transform its oil from a wealth that is spent into an economy that produces, and from an economy that produces into a future in which the Iraqi does not need to look at the dollar every morning to know the value of what he owns.
Rawabetcenter.com
 The significance of the Central Bank of Iraq’s recent statement lies not only in its reaffirmation of the country’s sufficient foreign currency reserves, but also in its timing and what it reveals about the nature of the pressures facing the Iraqi economy. On September 19, 2026, the Central Bank confirmed its ability to meet the demand for foreign currency to finance foreign trade, settle bank card transactions, and provide dollars to travelers at the official exchange rate.
 On Wednesday, the Prime Minister’s financial and economic advisor, Mazhar Muhammad Salih, revealed the most prominent features and challenges facing Iraq’s 2027 budget, stressing that its final form is not yet clear, pending the approval of the draft law by the Council of Ministers and its referral to the House of Representatives. Financialnews subscription
 The US State Department affirmed on Wednesday that the United States supports Iraqi Prime Minister Ali al-Zaidi’s efforts to extend state sovereignty and prevent attacks from being carried out inside or launched from Iraq, stressing Washington’s commitment to building a strong and mutually beneficial partnership with Baghdad. Economicnews reports
 The Middle Oil Company reveals its plan to increase production and meet the needs of power plants and refineriesThe Central Oil Company announced on Wednesday the signing of contracts to sell and pump oil through the strategic pipeline and Basra outlets. It also revealed a plan to increase production and meet the needs of stations and refineries in the coming days. The company’s Director General, Muhammad Yassin Hassan, stated in a statement to the official agency that “the Central Oil Company was producing 160,000 barrels per day before the export crisis, with production reaching about 90,000 barrels per day in 2023, and production rising to 160,000 barrels per day in 2025,” stressing that “the crisis of military escalation in the region led to a decrease in oil production.”
 Economic expert Nabil Al-Marsoumi identified five major obstacles facing Iraq’s budget for next year on Wednesday, while warning of a financial deficit that could exceed 60 trillion Iraqi dinars. Financialnews subscription
 A senior US official, speaking to the British newspaper The Independent on Tuesday (September 15), denied any plans to establish “security cooperation with Baghdad” after the scheduled withdrawal date of the 30th of this month.
 Member of the Coordination Framework, Uday Abdul-Hadi, confirmed on Tuesday that the process of voting on nine vacant ministerial portfolios in Ali al-Zidi’s government may extend into October, given the lack of a comprehensive agreement on setting a date for the decisive session in Parliament.
 On Tuesday, MP Abu Turab al-Tamimi revealed the role of Prime Minister Ali al-Zaidi, who “spared” Iraq from almost certain military strikes that were planned for yesterday by Saudi Arabia and the United States. Dailynews subscription
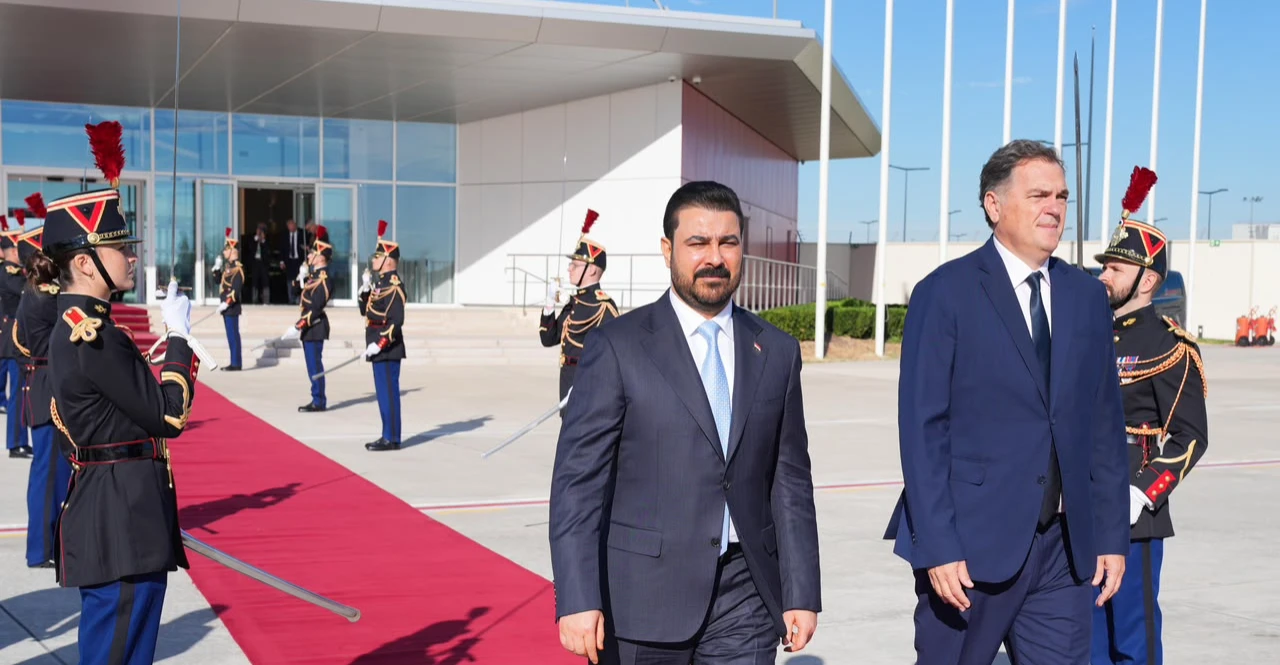 Iraqi Prime Minister Ali al-Zaidi headed to the German capital, Berlin, on Tuesday, after concluding his official visit to France.